One Person on Your Loan and Your Home, Start to Keys
Three Strangers, One Family in the Middle
I'm from the Chicago area. I spent fourteen years in Denver in banking and lending, and I've lived in Edwards, in the Vail Valley, for the last stretch of my career. Most of what I know about mortgages I learned on the lending side, watching the same thing go wrong over and over.
A family finds a house. Their agent writes an offer on a number the lender hasn't confirmed. The seller counters at seven at night and nobody on the buyer's side can say whether the new number works. The lender is waiting on the agent, the agent is waiting on the lender, and the insurance office hasn't been called at all. The family sits in the middle and hopes.
So I added the real estate license to the mortgage license and built the practice around one idea: the person placing your loan should be the person writing your offer, and the insurance should be quoted the week the file opens, not the week before signing day. Our insurance partner handles the policy. I handle the rest, personally.
Part of why this practice looks the way it does is personal. I've been through a divorce, and I know what it's like to sit across from an attorney wondering what happens to the house. That's why the divorce side of this practice is as careful as it is.
Four Things You Can Count On
- 01
The plan comes first.
The first call is a conversation about what you're trying to do, not a presentation. You leave with an action plan. The numbers go on paper after the application, when they're real, and we decide together.
- 02
Your number, not the bank's.
An approval letter is a ceiling. We start with the month you want to live with and work back to the loan and the house, not the other way around.
- 03
One desk.
The loan, the offer, the negotiation, and the insurance handoff run on one calendar, mine. When the seller counters at seven at night, the answer comes from the person who placed the loan.
- 04
I'll say what I see.
If the math doesn't hold, or waiting is the better move, or the loan you asked about isn't the one that fits, you'll hear it, and we'll get to the right answer together. I don't place loans to place loans.
Where I Work, and Who's on the Ground
I place loans anywhere in Colorado, the Front Range and the Western Slope, including the mountain markets where jumbo is the normal loan. I'm the agent of record in the Vail Valley and the Denver Metro. In the valley I'm at the showings myself. In the Denver Metro my showing team is on the ground with you, on your schedule, while I run the loan, the offer, and the negotiation from the same desk; you never wait on me to drive down. If you're buying in Fort Collins, Colorado Springs, or anywhere else, I place the loan and work with your local agent, because you deserve someone who knows the street.
Faith, Family, and the Mountains
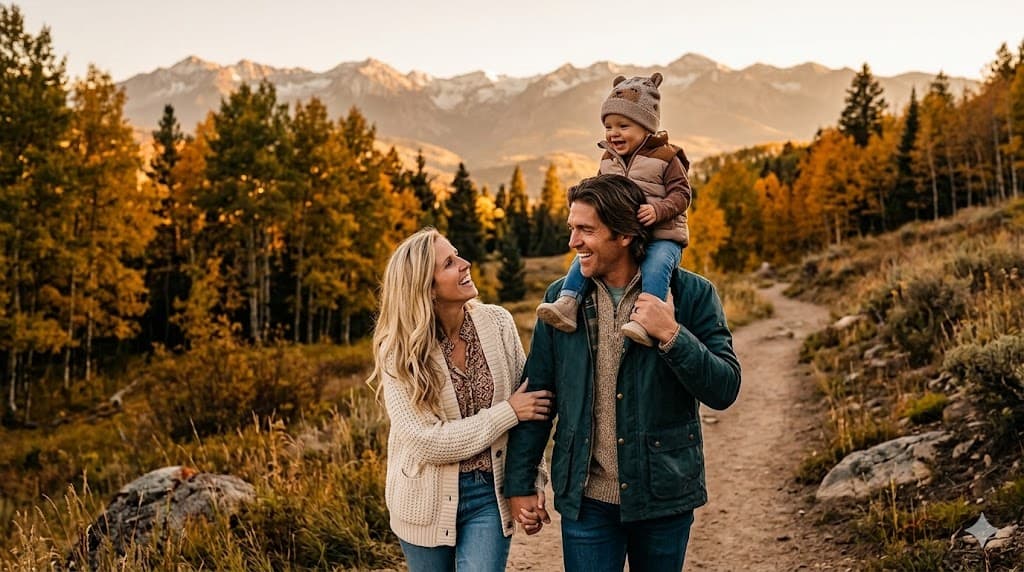
I'm married with a daughter, and I come from a close family; I bring that to how I work with yours. When I'm not working I'm skiing Vail and Beaver Creek, riding the valley in summer, on the golf course, or in the gym. That's what keeps me grounded, and it's why this practice lives here.
It Starts With a Conversation.
Tell me a little about what's going on and pick a time. That's the whole form. Twenty minutes, no presentation, no numbers yet. Your spouse, your kids, or your attorney are welcome on the call.
Loan programs, rates, and guidelines change. Nothing on this page is a commitment to lend.
Bobby Friel, licensed Colorado mortgage broker and licensed Colorado real estate broker, based in Edwards. Insurance through our insurance partner, Direct Insurance Services. 42 five-star Google reviews. (720) 799-2202 · info@cohomeequity.com.
Bobby Friel · NMLS# 332039 · Friel-Good Mortgage, Inc. · NMLS# 1901977 · Edwards, Colorado