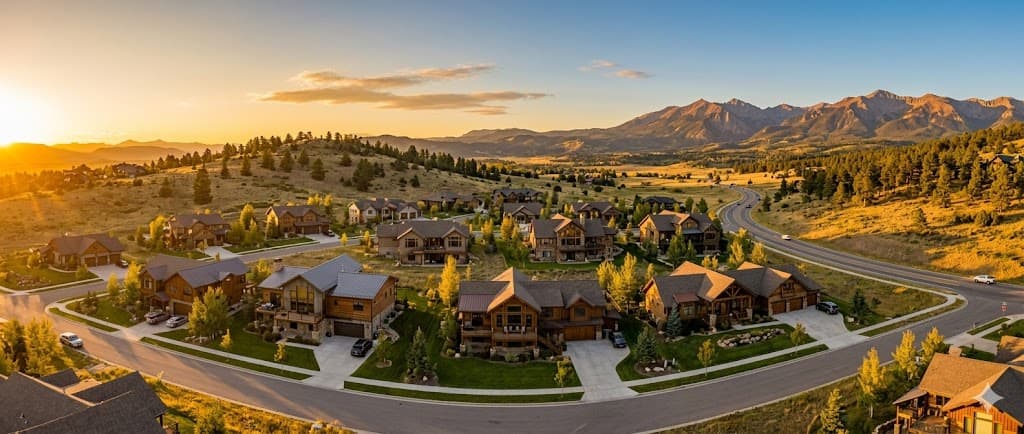
Colorado mountain homes — second home and vacation home loans
Mountain buyers · Colorado

Colorado Mountain Homes: Buy the Life. Get the Loan That Fits It.

First tracks on a powder morning. The river in June. A trail out the back door, a lake nobody else knows about, a free concert on a summer night, and a pace that makes the Front Range feel far away. That's what you're buying. The loan is just how you get there. The buyers who end up with the house they wanted up here sit down with me before they have a house in mind. We build the plan, the loan falls out of it, and when the right place comes up, you're the buyer who can move.
01 / SECOND HOME OR RENTAL
The lender's label sets the terms
02 / JUMBO IS NORMAL HERE
Most mountain loans run above the conforming line
03 / CONDOTELS INCLUDED
I have lenders who'll write them
04 / ONE DESK IN THE VALLEY
The loan, the offer, and the negotiation
Start here

What Are You Going to Do With the House?

Ski it all winter and hand the keys to the kids in spring. Raft and fish it all summer. Snowmobile, snowshoe, ride the bike paths, camp at the lake, sit on the deck and do nothing at all. Or rent it to people doing all of that while you're back at work. Every one of those is a real answer, and it's the first thing we talk about, because it's also the first thing a lender asks.

A second home you'll use yourself gets one set of terms. A rental you'll hardly visit gets another, with more down and a higher rate. The answer decides your rate, your down payment, the reserves you'll need in the bank, and whether the rent counts toward qualifying. It decides all of that before anyone looks at a house. So we settle it first, and then you go find the place knowing exactly what you can do when you find it.

What you've probably heard, and what's true:

  • 01

    "Mountain loans are hard to get."

    They're jumbo, which means more paperwork and reserves, not a wall. Most of the valley is jumbo. It's the normal loan here.

  • 02

    "The rent will cover it."

    Sometimes. On a second home, the lender doesn't count the rent. On a rental, a portion of it can count, with a management agreement or a rental history behind it.

  • 03

    "A condotel is just a condo."

    Not to a lender. A ski-in unit with a front desk and a rental program is a condotel, and most banks won't touch one. I have lenders who will. We check the building before you bid.

  • 04

    "Cash means I don't need any of this."

    You skip the loan. You still want someone who knows the building, the HOA, and what the unit really rents for.

Living here

Visiting Is Not the Same as Living Here

Mail doesn't come to the house in most of the valley; you get a box in town. Parking is a plan, not a given. Gas and groceries cost more than they do down the hill, and there are stretches of road where your phone is just a camera.

None of that is a reason not to buy. It's the difference between a buyer who's happy in year three and one who isn't, and I'd rather you hear it from me now than find it out after signing day.

I made this video for the people I talk to every week who are about to make the move. Watch it before you fall for a house.

What Living in a Colorado Mountain Town Actually Looks Like

Mail, parking, gas, cell service, and the cost of living, from someone who lives here.

What it takes

What Does It Do for You When the Lender Is Also at the Table?

Most mountain buyers bring three strangers to the purchase: an agent, a lender somewhere on the Front Range, and an insurance office. None of them talk. The offer gets written on a guess, the loan gets sorted afterward, and the appraisal date gets picked by someone who has never met a mountain appraiser. Up here that costs you houses, and it costs you money on the ones you get.

When the person writing the offer is the person placing the loan, the purchase runs differently, and the difference is yours.

What that looks like when we're standing in the house:

  • 01

    The number, live.

    Once your file is built, I can run the real payment on the place we're walking through, on the spot. Not a guess, not "let me check with my lender." You know what you're writing before we leave the driveway.

  • 02

    An offer the other side takes seriously.

    The listing agent knows the loan is already placed, so when we're firm on price or dates, they know it holds. That's leverage you don't get with a pre-approval from a stranger.

  • 03

    Concessions that actually work for you.

    If the seller gives something back, I know how to point it: at points that lower your rate for years, or at the costs you'd otherwise pay at signing. Most agents ask for a credit and stop there.

  • 04

    Dates that fit a mountain file.

    Jumbo appraisals up here take longer, and a contract that ignores that puts your earnest money at risk. I set the appraisal and loan dates where they need to be before we sign.

Bobby Friel, CO Home Equity

The house doesn't pick the loan. The plan for the house picks the loan. Get the plan straight and the rest is paperwork.

— Bobby Friel · CO Home Equity

CALIBRATED QUESTION

If the seller knew your loan was already placed, and the person who placed it was at the table, how would that change the offer?

Which loan

Second Home, Rental, or Primary?

Second home

  • You'll use it yourself for part of the year and may rent it when you're away.
  • Better rate and lower down than a rental.
  • The rent doesn't count toward qualifying.
  • Most mountain buyers land here.

Rental

  • You'll rarely stay there; it earns.
  • More down, a higher rate, more reserves.
  • A portion of the projected rent can count.
  • If the plan is a rental first, that's a DSCR conversation, and it's on its own page.
PrimarySecond homeRental
You live thereMost of the yearPart of the yearRarely
RateLowestA step higherHigher still
Down paymentLowestMoreMost
ReservesSomeMoreMost
Rent counts to qualifyNoNoA portion can
Renting it outNoWhen you're awayYear-round
Jumbo availableYesYesYes
FitsMoving to the mountainsWeekends, seasons, familyInvestors

If you'll be in the house for real stretches of the year, second-home terms are yours and they're the better terms. If you won't, say so — a rental loan costs more, and it's the one that's true.

Your number

What Would a Mountain Home Cost a Month?

Price, down, rate, and term, then the three lines most buyers forget: taxes, insurance, and HOA. Mountain HOA dues and insurance run higher than the Front Range, so put real numbers in those two.

$625,000
10% · $62,500
6.500%
$
$
$

Monthly payment, fully loaded · 30-yr fixed

$4,343 / mo

Working range $4,100–$4,600

Principal & interest$3,555
Property tax$286
Homeowner's insurance$267
Monthly PMI$234

PMI

Under 20% down means PMI — and it's not the penalty people think. It's what lets you buy the home you want now instead of the one that's left after two years of saving. Your number depends on credit score, property type, and term — and we shop it. We'll price it together.

This is an estimate on the numbers you entered. A second-home or rental loan prices differently from a primary, and jumbo files carry their own reserve rules. The real figure comes from the conversation.

Want to see what the plan looks like on a real house?

Full payment calculator

Fit

Is a Mountain Home Right for You Now?

Usually, when:

  • You know what you'll do with the house, even if the town is still an open question.

  • The down payment is real: savings, equity in your current home, or cash for the whole thing.

  • Your budget carries the place through a slow season, whether or not it rents.

  • You want the purchase to go right, not just a rate. If you're shopping for a quote, I'm the wrong call; if you want the plan, I'm the right one.

Usually not, when:

  • The plan only works if it rents every week of the year.

  • The reserves would be gone the day you sign.

  • You want a rental first and a place to stay second. That's an investment loan, and we run it that way.

  • You're buying in Telluride or Durango and need a buyer's agent there. I'll place the loan; the showings need someone local.

Two buyers

How It Usually Goes

Illustrative, not specific clients

The Denver couple who started with the plan.
FILE 01

The Denver couple who started with the plan.

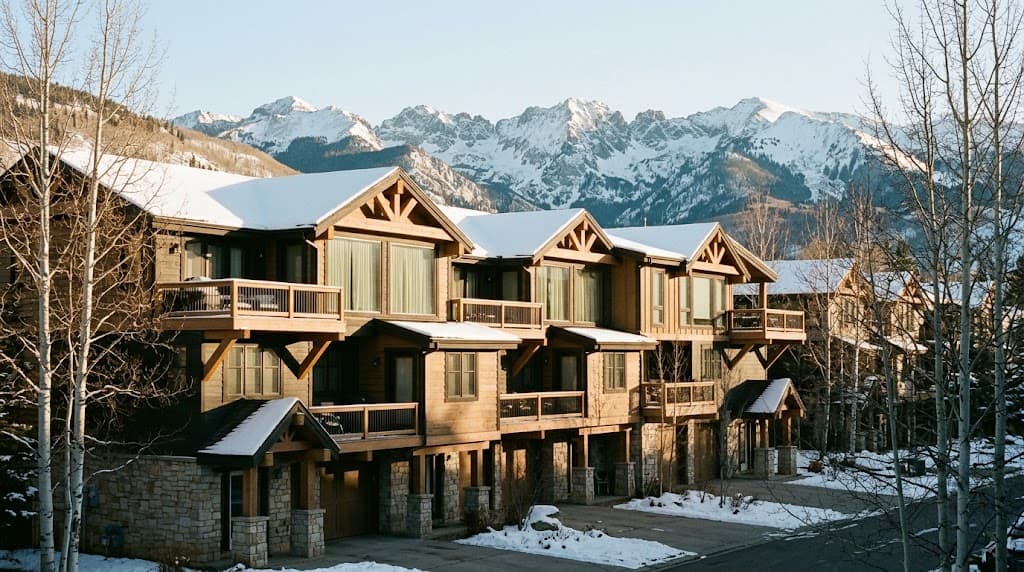
They wanted an Eagle-Vail townhome for ski season and summers on the river, and came to me before they'd looked at a single unit. We built the file as a second home, drew the down payment from the equity in their Denver house, and had insurance quoted the first week. When the right unit listed, we ran the payment standing in the living room, wrote firm on price with a seller credit pointed at points, and the listing agent took it over a higher offer with a loan nobody had seen. Keys about seven weeks later, in time for opening day.
The Springs family with a rental plan.
FILE 02

The Springs family with a rental plan.

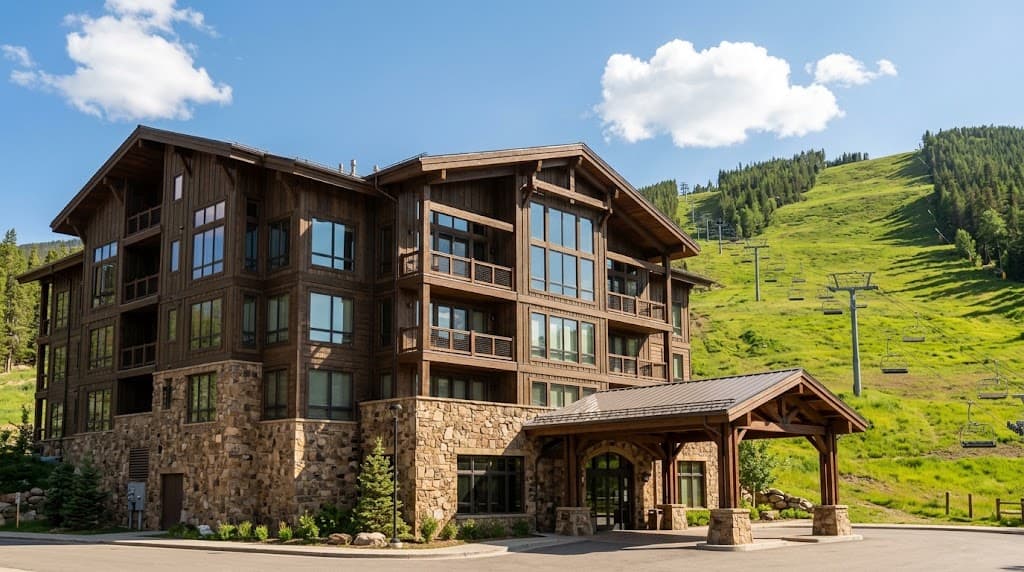
They wanted a Breckenridge condotel, and the answer was that they'd be there a handful of nights a year. We ran it as a rental from the start, with more down, real reserves, and the management agreement in the file, and put it with a lender who writes condotels before they bid. Nothing surprised the underwriter. That's the whole point.

The process

From the Town to the Keys

One desk in the valley, the loan and the offer. Six to eight weeks from contract to keys up here, and we build the dates around that. Paying cash? Skip steps two and three and go straight to the offer.

01

The first call

The town, the plan for the house, and where the money's coming from. You leave with an action plan and a loan type.

02

The application, week one

Through my secure client portal, or by phone. Income, assets, reserves, and the home you already own if we're drawing on it. Our insurance partner quotes the property the same week, so it's out of the way.

03

The strategy

What the first call and the application told us, on paper: the loan, the number, and the path from here to the keys. Priced as a second home and, if it's close, as a rental beside it. We pick together.

04

The offer

In the Vail Valley I write it, with the loan already placed and the building already checked, and I negotiate it: price, dates, and any credit pointed where it does you the most good. Elsewhere in Colorado, I work with your agent.

05

Appraisal and underwriting

Jumbo appraisals in the mountain counties take longer than the Front Range. The contract dates already know that.

06

Signing day

Papers, keys, and the pass you already bought.

Questions

Mountain Home Loans in Colorado — Questions Answered

More than a primary and less than a rental. The exact share depends on the loan size and whether it's jumbo. We run it on the first call.
On a second-home loan, no. On a rental loan, a portion of projected rent can count, with a management agreement or rental history. If the plan is rent-first, see the DSCR page.
Whether you use it yourself for real stretches of the year. Rent it when you're away and it can still be a second home. Rarely visit and it's a rental.
In the Vail Valley, Summit, and the Roaring Fork, usually yes. Jumbo means more reserves and documentation. It's the normal loan in these counties, not a special case.
Often, yes. It's the most common way Front Range buyers fund a mountain purchase without selling investments. We look at your equity on the first call.
Yes. A ski-in unit with a front desk and a rental program is a condotel, and most banks won't write one. I place them with lenders who do, and we check the building before you bid.
Six to eight weeks from an accepted offer to keys is typical up here, mostly because jumbo appraisals take longer. Cash buyers move faster.
Because the offer and the loan get negotiated as one thing: the real payment at the showing, firmness the seller can see, credits pointed where they help you, dates set for a mountain appraisal. In the Vail Valley and the Denver Metro I do both.
Bobby Friel — CO Home Equity Founder

Pick the loan before you pick the house.

I live and work here in the valley. I ski it and I ride it, and I know why you want a piece of it. I also know how most people buy up here: house first, loan second, three strangers who never talk, and a contract written by whoever got there first. That's how you lose the house, or overpay for the one you get.

I don't write pre-approvals for rate shoppers. I build the purchase with you, from the plan for the house through the loan, the offer, and the negotiation, and I do it as the one person at the table who can see all of it. If that's what you want, the first conversation is where it starts.

The house will still be beautiful. You'll just be the buyer who gets it.

Your mountain plan

Start With the Plan. The House Comes Next.

One conversation about how you'll use the place and where the money's coming from. You leave with an action plan and a loan type, and when the right house lists, you're the buyer who can move on it.

Second-home and investment loans are priced by how the property will be used. Rates, reserve rules, and loan limits change by county and by file. Every figure on this page is an estimate until your file is underwritten.

Second-home, jumbo, condotel, and investment loans placed by Bobby Friel, licensed mortgage broker and licensed real estate broker, based in Edwards and serving buyers across Colorado. Insurance through our insurance partner. 42 five-star Google reviews. (720) 799-2202 · info@cohomeequity.com.

Bobby Friel · NMLS# 332039 · Friel-Good Mortgage, Inc. · NMLS# 1901977 · Edwards, Colorado