Colorado home bought with an FHA or VA loan
Home loans · Colorado

FHA and VA Loans in Colorado

FHA and VA are the two government-backed ways to buy a home with little or nothing down. One is open to almost anyone; the other is earned through service and, if you have it, usually costs less to carry. I place both, and I'm also a real estate broker, so the loan and the house get planned by one person.
FHA
Small down payment, flexible credit
VA
Nothing down, no monthly mortgage insurance
COLORADO
Higher limits in the mountain counties
ONE PERSON
Your loan and your house, planned together
Start Here

Two Loans That Get Called "Government Loans" and Behave Nothing Alike

Most buyers who ask me about FHA have been told it's the loan for people with bad credit. Most veterans who ask about VA have been told sellers won't take their offer. Both ideas are years out of date, and both cost people money every month.

FHA is a loan the government insures so a lender can accept a smaller down payment and a thinner credit file. You pay for that insurance, up front and every month, and on most FHA loans it never goes away. VA is a loan the government guarantees for people who served. There is no down payment, no monthly mortgage insurance, and the rate is usually the lowest on the board. If you're eligible for VA, the question is rarely FHA or VA. It's VA or conventional, and we'll look at that on the same page.

You’re probably thinking:

  • 01

    "FHA is for people who can't qualify for anything else."

    It's for people whose down payment or credit file doesn't fit the conventional box today. Plenty of them have strong income. The trade is the mortgage insurance, and we'll talk about how to get out of it later.

  • 02

    "Sellers don't take VA offers."

    Some agents still believe that, and they're wrong. A VA appraisal has a few extra checks on the condition of the house. That's it. In a market that's cooled, a clean VA offer with a real pre-approval competes fine, and I write the offer myself.

The Real Reason

The Down Payment Isn't the Decision. The Monthly Is.

Buyers pick FHA or VA because of the down payment. Then they live with the payment for years. The right question is what each loan costs to carry every month once the insurance, the funding fee, and the rate are all in, and whether that payment still fits the year after the furnace goes.

FHA's monthly insurance is the piece people forget. VA's funding fee is the piece they don't know about; it's usually rolled into the loan and waived entirely for veterans with a service-connected disability rating. Conventional has its own insurance that drops off once you have enough equity. Three loans, three different monthly stories on the same house. That's what the second call is for: your numbers, all three side by side, before you write an offer.

The three questions I’ll ask you:

  • 01

    Have you or your spouse ever served, even for a short stint in the Guard or Reserve?

  • 02

    What's the most you'd be comfortable paying each month, before we look at what you could qualify for?

  • 03

    If the house you want is in a mountain county, have you checked whether it's inside the loan limit, or are we solving that too?

Bobby Friel, CO Home Equity

I've placed FHA loans for people with great credit and VA loans that beat every conventional quote in the room. The loan doesn't know your story. It only knows the numbers, and we'll know them before we pick.

— Bobby Friel · CO Home Equity

CALIBRATED QUESTION

If the monthly payment were the same on both, which would you rather have: a smaller loan with insurance for life, or the bigger one with none?

The Comparison

FHA, VA, and Conventional on One Page

Open to almost anyone

FHA

FHA
  • Who it suits: A modest down payment or a credit file that's still healing
  • The trade: You pay for the insurance, up front and monthly
  • Colorado note: Mountain counties carry higher limits than the Front Range

Earned through service

VA

VA
  • Who it suits: Anyone who served and meets the service requirement, including many surviving spouses
  • Down payment: None
  • Mortgage insurance: None monthly; a one-time funding fee, waived with a disability rating
  • Loan limit: None for buyers with full entitlement
FHAVAConventional
Who qualifiesAny buyer who fits the guidelinesVeterans, service members, some Guard and Reserve, eligible surviving spousesAny buyer who fits the guidelines
Down paymentSmallNoneSmall to moderate; larger avoids insurance
Mortgage insuranceUp front and monthly; usually for the life of the loanNone monthly; one-time funding fee, often rolled in, waived with a disability ratingMonthly until you reach enough equity, then it drops
Credit postureMost forgivingForgiving; residual-income test matters more than scoreLeast forgiving
Loan size in ColoradoCounty limit; higher in mountain countiesNo limit with full entitlementCounty limit; jumbo above it
OccupancyMust be your homeMust be your homeHome, second home, or rental
Someone can assume itYes, if they qualifyYes, if they qualify; entitlement stays tied until releasedNo
Best forThin down payment, rebuilding creditAnyone eligibleStrong credit, real down payment, or a second home

If you're eligible for VA, start there. It wins on the monthly more often than not.

If you're not, FHA versus conventional comes down to your credit file and how long you'll keep the loan. That's a numbers question, and we answer it together on the second call.

$625,000
10% · $62,500
6.500%

Monthly payment · 30-yr fixed

$4,109 / mo

Working range $3,900$4,300

That's your starting number. The exact figure comes from a conversation, not a form.

Start a Conversation

Full calculator

The Straight Answer

Who These Loans Fit

A good fit

FHA or VA Is Usually Right When…

  • You served, or your spouse did

    VA first, every time.

  • Your down payment is small

    You'd rather buy this year than save for three more.

  • Your credit took a hit

    And it has been healing for a while.

  • You're buying the home you'll live in

    Both loans are built for an owner-occupied house.

Another door

Usually Not the Answer When…

  • You have a real down payment and strong credit

    Conventional will likely cost less to carry.

  • The house is a second home or a rental

    FHA and VA are for the home you occupy.

  • The price is above the county limit and you're not VA-eligible

    That's a jumbo conversation.

  • You're planning to refinance the day rates drop

    We plan the loan you'd be fine keeping.

Illustrative, not specific clients

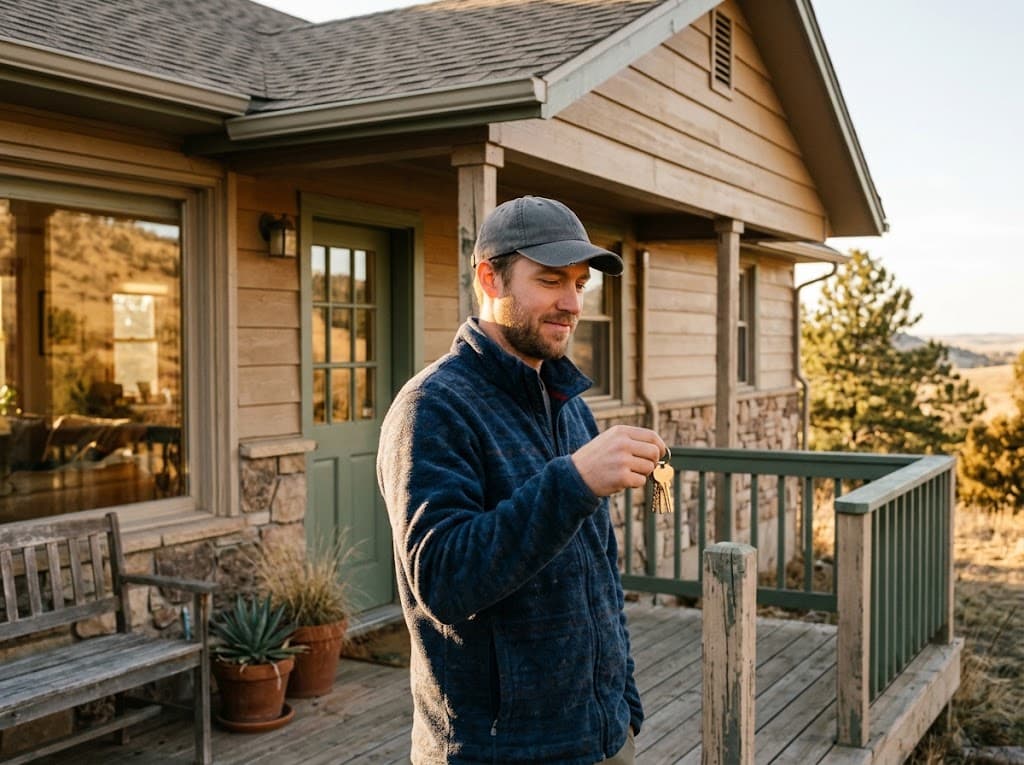
A buyer on the porch of a Front Range home, keys in hand
FILE 01

The sergeant who was told to go FHA

He'd been out of the Army four years and a lender had him pre-approved FHA with a down payment his parents were helping with. On our first call I asked one question: had he ever served. He had his certificate of eligibility within a week. VA, nothing down, no monthly insurance, and the parents' money stayed in the parents' account. The offer was accepted the second weekend out.
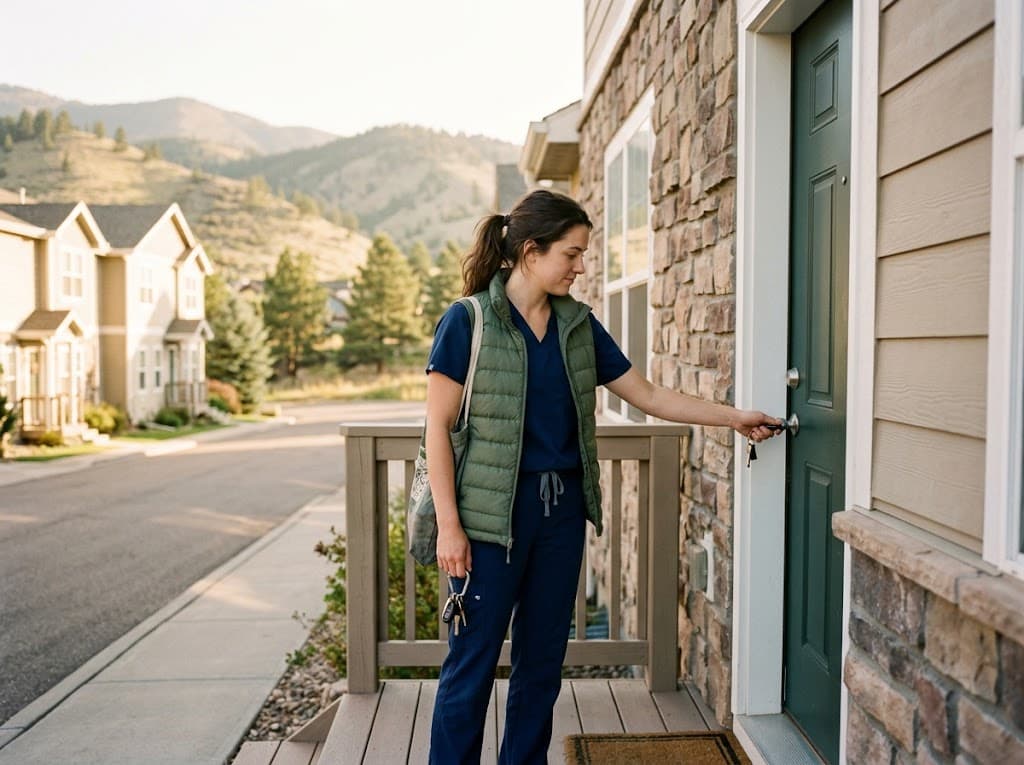
A buyer in scrubs unlocking the front door of a small townhome
FILE 02

The nurse with the thin file

Two years out of school, good income, a credit file that was mostly a car loan and one card. Conventional wanted a bigger down payment than she had. FHA didn't. We ran the monthly with the insurance included so nothing surprised her later, planned the equity path to a conventional refinance as a bonus rather than a promise, and she was at signing day in a month.

What Happens Next

First Call to Signing Day

Here's how it goes, from the first conversation to the keys.

01

The first call

A meet-and-greet.

We talk about the house you want, the month you can carry, and whether you've served. You leave with an action plan, not a pitch.

02

The application

Through my secure client portal, or by phone if that’s easier.

For VA, we request your certificate of eligibility at the same time.

03

The second call

Now there's real data.

FHA, VA, and conventional, side by side, on your numbers. We pick together.

04

The pre-approval and the offer

A pre-approval built on verified income, not a guess.

If I'm also your agent, I write the offer the same day.

05

Appraisal and underwriting

FHA and VA appraisals check the condition of the house a little harder.

I've seen what they flag, and we handle it before it's a problem.

06

Signing day

Papers, keys, done.

Our insurance partner has the policy bound before you sit down.

Timing depends on the house and the file. Most of my buyers are at signing day within about a month of an accepted offer.

FAQ

FHA and VA in Colorado — Questions Answered

Yes. FHA exists for exactly that. You'll pay mortgage insurance up front and monthly, and Colorado's mountain counties have higher FHA limits than the Front Range. We run the full monthly, insurance included, before you decide.
Veterans, active-duty service members, many Guard and Reserve members, and eligible surviving spouses, subject to the service requirement. Your certificate of eligibility settles it. I request it during the application so there's no guessing.
If you're eligible, almost always. No down payment, no monthly mortgage insurance, and usually a lower rate. The one-time funding fee is often rolled in and is waived with a service-connected disability rating.
On most FHA loans, not unless you refinance or sell. That's the real cost of FHA, and it's why we plan the equity path to a conventional loan as a bonus rather than the plan.
Yes. Entitlement restores when the prior VA loan is paid off, and in some cases a veteran can hold two VA loans at once. It depends on remaining entitlement, which we check up front.
Yes. FHA limits are higher there than on the Front Range. VA has no limit for buyers with full entitlement, which is why VA buyers can compete in the valley without a jumbo loan.
A good one will. The extra appraisal checks are about the condition of the house, not you. I write the offer, explain the loan to the listing agent, and keep the file clean so there's nothing to object to.
No. Both require the home to be your primary residence. If you're buying a rental or a second home, that's a conventional or investment-property conversation, and I do those too.
Bobby Friel — CO Home Equity Founder

Bobby's Take on FHA and VA

I've been in lending since before FHA and VA were the loans everyone forgot to explain. The pattern hasn't changed: the buyer hears one word from a friend, a lender confirms it because it's easy, and the buyer carries the wrong loan for a decade.

VA is the best consumer mortgage in America, and I've watched eligible buyers get steered into FHA because nobody asked a question. FHA is a fine loan for the right file, as long as you go in knowing what the insurance costs and what it would take to leave it behind.

You'll get both from me, on paper, with your numbers, before we pick. And because I'm also the broker on the house side for many of my buyers, the loan and the offer are built by the same person. That's the whole point of doing it this way.

ONE CALL

Let's Find Out Which One Fits.

One call. No pitch. You leave with a plan and a straight answer about FHA, VA, or neither.

FHA and VA loans placed by Bobby Friel, licensed mortgage broker (NMLS# 332039, Friel-Good Mortgage, Inc. NMLS# 1901977) and licensed real estate broker, based in Edwards and serving homeowners and buyers across Colorado. Insurance through our insurance partner. 42 five-star Google reviews. (720) 799-2202 · info@cohomeequity.com.